Optional Home Insurance Coverage Upgrades for Florida Homeowners
A standard home insurance policy is an important foundation, but optional coverage upgrades may help close costly protection gaps for Florida homeowners.
Jump to a Section
Why Optional Coverage Upgrades Matter for Florida Homeowners
Florida homeowners face property risks that can go beyond what many people think of as a basic home insurance policy. Wind exposure, water-related damage, storm activity, rising rebuilding costs, and stricter repair conditions can all affect how well a standard policy responds after a loss.
Optional coverage upgrades exist to help strengthen protection in areas where the base policy may have lower limits, exclusions, or no coverage at all. These upgrades do not mean every loss is covered, but they can improve how a policy responds in important situations depending on the insurer and policy structure.
The Dupuy Insurance Team helps homeowners review which coverage upgrades may make sense based on the home, the location, and the owner’s risk tolerance.
Popular Optional Coverage Upgrades
Click each section to expand more details.
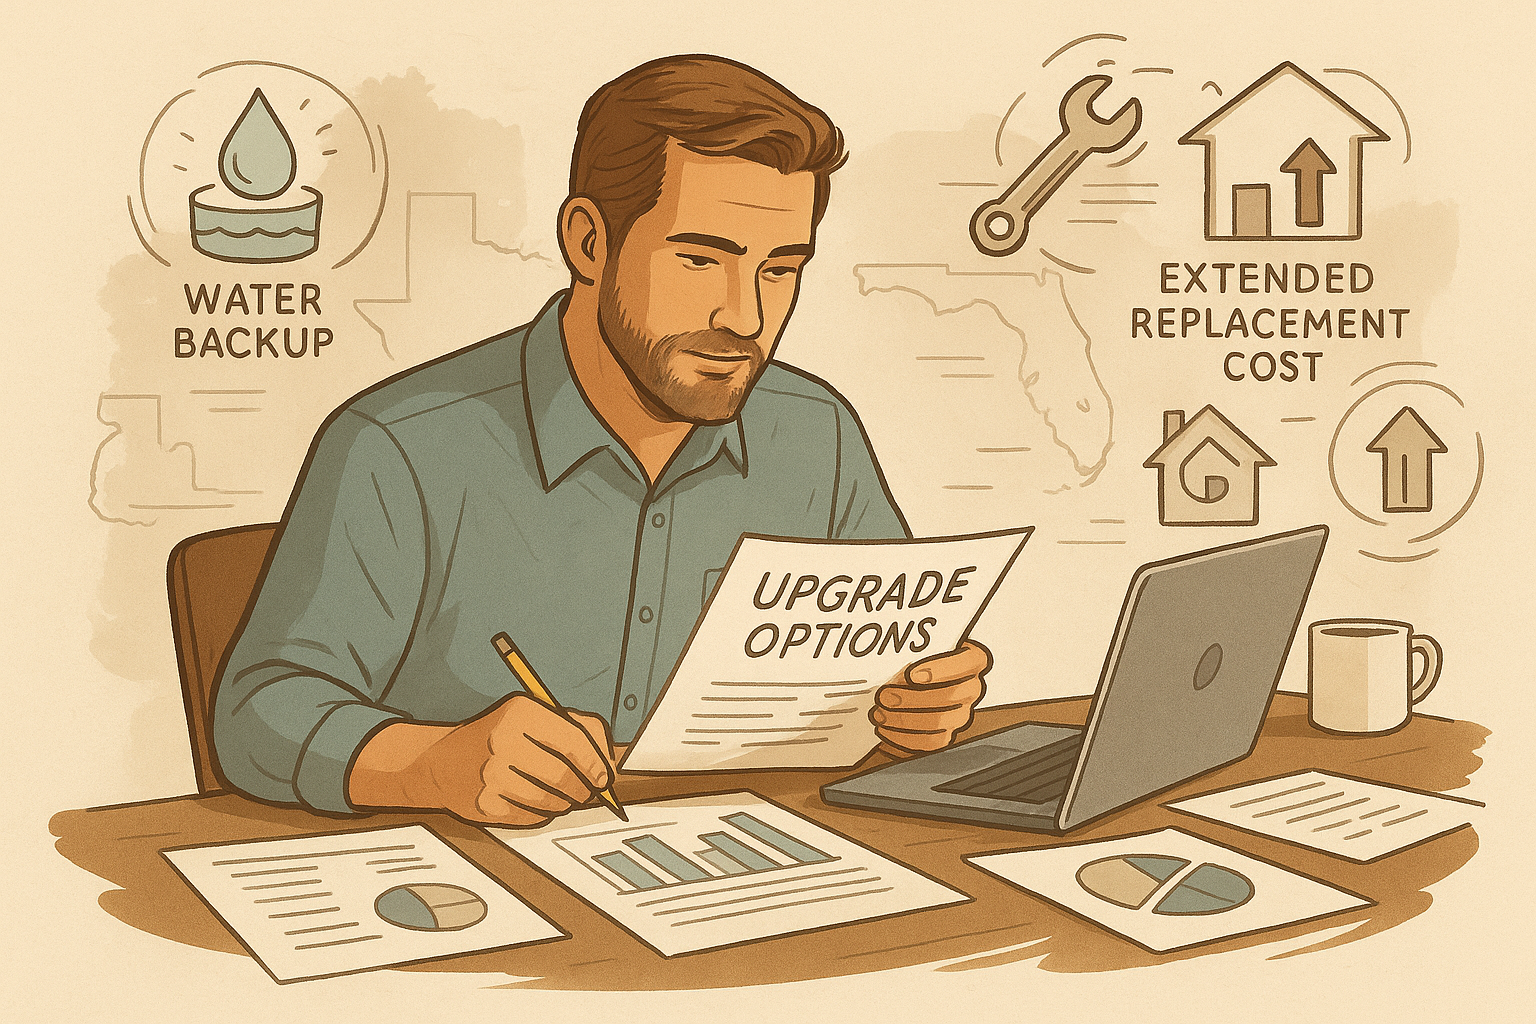
Extended Replacement Cost for the Dwelling
Construction costs can increase after storms, material shortages, or inflation. Extended replacement cost may provide an added layer of protection if dwelling limits prove insufficient after a covered loss, subject to policy terms.
Water Backup and Sump Overflow Coverage
Water backup losses can be expensive and may not be covered under a standard policy without an added endorsement. This coverage may help in certain situations involving drain or sewer backup, depending on the policy.
Service Line Coverage
If a buried utility line serving the home fails, repair costs can be substantial. Service line coverage may help with certain repair and restoration costs for covered utility line failures on the property.
Home Systems or Equipment Breakdown Coverage
Equipment breakdown coverage may help with certain sudden mechanical or electrical failures involving home systems or appliances, depending on the coverage form and exclusions.
Ordinance and Law Coverage
If part of the home must be rebuilt to meet current building codes after a covered loss, ordinance and law coverage may help with some of those added costs, subject to limits and policy terms.
Personal Property Replacement Cost
Instead of settling covered personal property losses on a depreciated basis, this upgrade may allow replacement-cost settlement if the policy includes that feature and its requirements are met.
Wind or Hurricane Deductible Options
Florida homes often have separate wind or hurricane deductibles. Depending on the insurer, deductible structures and options may vary and should be reviewed carefully.
Identity Theft Protection
Some insurers offer endorsements that may help with certain identity theft recovery expenses or support services, depending on the policy design.
Increased Liability Coverage
Higher personal liability limits may be worth reviewing for homeowners with pools, pets, frequent guests, or other factors that could increase liability exposure.
Scheduled Protection for High-Value Items
Jewelry, artwork, collectibles, and other valuable items may need separately scheduled coverage because standard policy sublimits may not be enough.
How Optional Upgrades May Help Long-Term
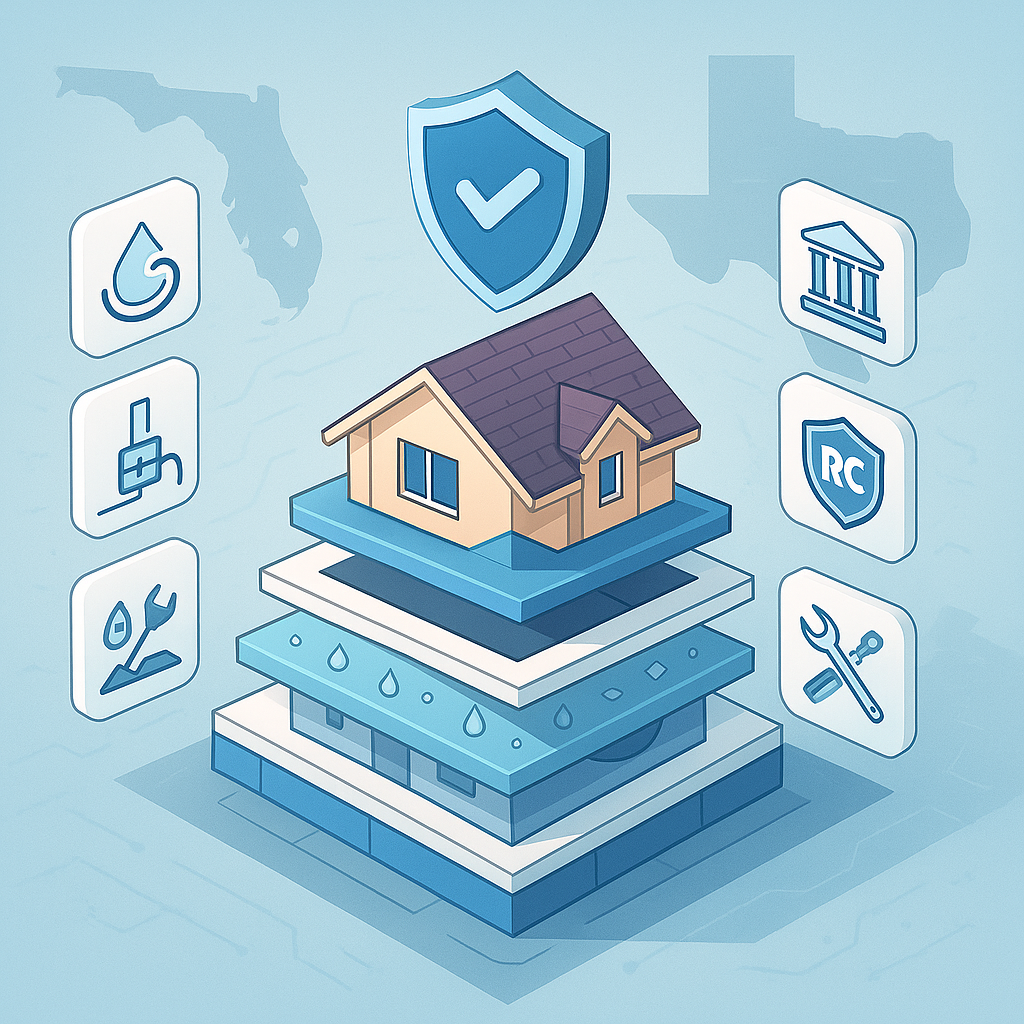
Insurance is not only about repairing physical damage. It is also about managing financial shock after a loss. Optional upgrades can sometimes reduce out-of-pocket strain by improving how the policy responds in situations where base coverage would otherwise be limited.
Help reduce out-of-pocket costs
Help address coverage gaps before a claim happens
Support better financial predictability after certain losses
Help protect higher-value property and home systems
Support a more complete insurance structure
Many of these upgrades may cost far less than the uncovered portion of a major home loss. The key is reviewing them before a claim happens, not after.
Why Homeowners Work With The Dupuy Insurance Team
- Clear explanations: We explain coverage options in simpler terms.
- Carrier comparison: We help review options from participating insurers where available.
- Property-focused guidance: We look at what upgrades may fit your home’s actual risk profile.
- Savings review: We help identify potential credits, discounts, or structure improvements where available.
Many homeowners do not realize where their biggest policy gaps are until after a loss. Reviewing optional upgrades in advance can help build a more complete protection strategy.
Frequently Asked Questions About Optional Coverage Upgrades
Does a standard home insurance policy cover everything?
No. Standard policies often have exclusions, sublimits, deductibles, and conditions that can leave important gaps depending on the type of loss.
Are optional upgrades worth it?
They may be, depending on the home, the location, and the homeowner’s risk tolerance. The best approach is to compare cost against the type of gap the endorsement is meant to address.
Which upgrades matter most in Florida?
Water-related protection, ordinance and law, service line coverage, stronger dwelling protection, and deductible structure are all worth reviewing.
Can you help me review which upgrades fit my home?
Yes. The Dupuy Insurance Team can help review home insurance options and discuss which optional endorsements may make sense for your situation.
The Dupuy Insurance Team